Anybody Buying Yet? Where’s the Bottom?

I’ve been saying this for years.

The only way that you won’t be left in the dust financially is to make sure that you hitch your wagon to the world‘s most powerful horses.

If you don’t, you’re going to be left sitting there….wondering where everyone went.

If the horses die, you won’t be any worse off than what you were going to be anyhow.
 
Last edited:
I’ve been saying this for years.

The only way that you won’t be left in the dust financially is to make sure that you hitch your wagon to the world‘s most powerful horses.

If you don’t, you’re going to be left sitting there….wondering here everyone went.

If the horses die, you won’t be any worse often than what you were going to be anyhow.
Seems @PoleX is a good horse to hitch to.
 
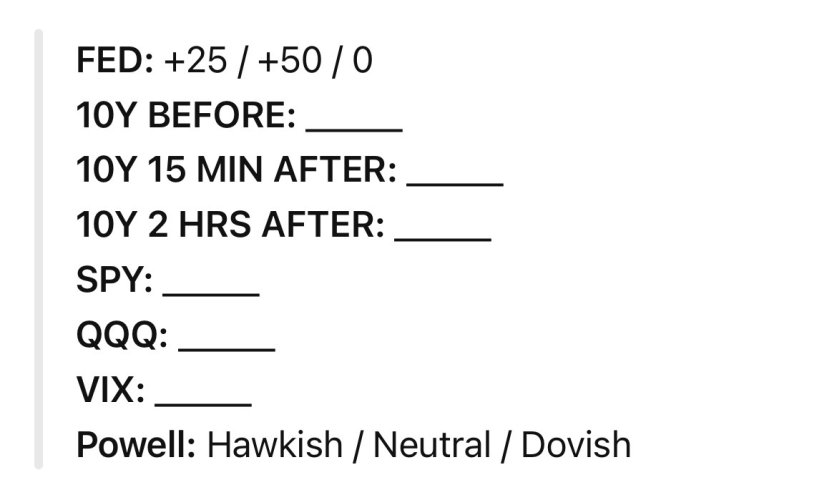
I’m laying low through the fed announcement…watching 10yr. Here’s my AIngenerated cheat sheet:
IMG_2900.jpeg
I dca’d into AI/chips for the last 5 years. Took some off the top and went against my conservative nature and yolo’d into SaaS as I posted about back in June. I bought like 20k worth of deep in the money call options...every dog has its day. FA's and I don't get along very well.
 
I’ve been saying this for years.

The only way that you won’t be left in the dust financially is to make sure that you hitch your wagon to the world‘s most powerful horses.

If you don’t, you’re going to be left sitting there….wondering where everyone went.

If the horses die, you won’t be any worse often than what you were going to be anyhow.
Worth reading that twice...totally agree.
 
I’m not the expert that many of you are, but I don’t see how the market has not had a serious correction. There are so many negative forces right now. Any thoughts? Do we inflate the bubble more before it pops? Am I totally out of touch with what’s going on?


Same here

It feels like a giant oak dining room table has a missing leg, so the decision has been to hold up that corner with a toothpick.

Seems about right. The one positive the market has going for it is that earnings are great. Some of that is from accounting "magic", but Energy earnings are real - ask anyone who drives a gas vehicle. Maybe another positive is the market has become too big to fail. Retired people (at least those who invested) are spending like crazy and young people can't buy a house so they YOLO it is the stock market to Kalshi bets. What could go wrong?

What is undeniable is the equity risk premium (expected excess returns to bonds given the risk taken), has compressed a lot with the 10yr bond going to 5%.


Am I the only one who is positive on the market? Seems like there are always waaaaay more negative posts here on the overall market than positive. There are ALWAYS things to worry about but the vast majority of them don't matter. Hence why I am nearly always positive.

A 10% correction is just normal and always a possibility but I'm buying here. Would probably put on more leverage on a pullback.
 
Am I the only one who is positive on the market? Seems like there are always waaaaay more negative posts here on the overall market than positive. There are ALWAYS things to worry about but the vast majority of them don't matter. Hence why I am nearly always positive.

A 10% correction is just normal and always a possibility but I'm buying here. Would probably put on more leverage on a pullback.
I’m cautiously positive. There’s always two sides to a coin. Nephew bought his first house recently on his own without help. Basic two income couple out of college situation. I have another similar first house situation locally. New home buyers continue to exist. Company financials have been strong overall. Fed seems to remain independent. Employment remains full at 4.1%.

My concern would be the information I see lags by a quarter, mostly. Fuel costs are a problem until they aren’t.
 
Am I the only one who is positive on the market? Seems like there are always waaaaay more negative posts here on the overall market than positive. There are ALWAYS things to worry about but the vast majority of them don't matter. Hence why I am nearly always positive.

A 10% correction is just normal and always a possibility but I'm buying here. Would probably put on more leverage on a pullback.
I guess I'm positive, but not overly so. The things to worry about do matter in short to medium run - inflation, rates, etc. If interest rates get high enough to attract capital, that is capital that doesn't go into the stock market. It is never a matter of 'if' I'm in the market. It's a question of what size and what markets.

10% correction? When was that? I would love to buy it as well. We are down 2% off ATH.
 
AI is the massive market driver along with strong earnings with positive outlooks. My retirement TSP is making hand over fist $$$ though the challenge with that - it's a strong flag volatility flag (imho), be it a correction (10-15%) or a softening of the inflation rate miraculously occurs w/o fed stepping in.
I believe (basic joe opinion) we are going to feel a dip before the Fed makes the announcement - fear is too high that rates are going to be used to temper the inflation and a correction drop if rates are used to temper the setting. Tommorw creeped up quick... ;)

What to do... 2.5 from retirement. I have been pressing hard on Large 60% and small cap 40% though I've moved 40% to the G fund to hold over for 2-3 year use once my madatory retirement kicks in while the 60% continues to ride the large cap world, stepping out of the "big beautiful" small cap epi-center soon to hit.

Mallard mentioned the strong horses... agree. small cap gains are sweet though - those ponies may tire out. Morgans and clyds for the pulling... :)
 

Interesting update from Bank of America:

Consumer spending held up through the summer, says BofA​

Consumer spending remained hot through the summer, even as Americans faced down continued over-target inflation, according to a new survey from Bank of America.

Total credit card spending rose 4.5% year-on-year in August, per the BofA survey results published Tuesday. That's more than four times last year's average pace, the survey found. Month-on-month, spending accelerated by 0.9%.

https%3A%2F%2Fd29szjachogqwa.cloudfront.net%2Fimages%2Fuser-uploaded%2Fscreenshot-2026-09-15-at-114033-am_3561.png

Total card spending per household rose 4.5% year-over-year, per Bank of America. Chart: Bank of America Institute ·Bank of America Institute
"Americans are still ramping up their discretionary spending across both goods and services," Liz Everett King, head of the Bank of America Institute, and BofA senior economist David Tinsley wrote.

Some of that uptick in spending was driven by higher gasoline prices, which have complicated the Fed's path forward as the war in Iran shows no sign of slowing down. Excluding gasoline, spending rose 3.7% year-on-year in August, per the survey.

Even so, per King and Tinsley, the data suggests that "consumers are increasing their spending because they want to and not because they have to."
 
I guess I'm positive, but not overly so. The things to worry about do matter in short to medium run - inflation, rates, etc. If interest rates get high enough to attract capital, that is capital that doesn't go into the stock market. It is never a matter of 'if' I'm in the market. It's a question of what size and what markets.

10% correction? When was that? I would love to buy it as well. We are down 2% off ATH.
You're positive? Maybe I've been reading you wrong on this entire thread but I would have put you at cautious at best. It seems like you normally have a negative bias.

Inflation, interest rates and oil have all gone higher this year and yet so have stocks. Inflation has gone from about 2.4% to 3.4%. The 10 year has gone from roughly 4.15% to around 5%. WTI has gone from below $60 to over $100 now. And yet the S&P is up around 10%. I guess without the stellar earnings growth this year, it would be a little different. My point though that I've made many times is that it just rarely pays to worry about the vast majority of stuff and to try and jump in and out. Or to wait for a correction to buy. Maybe it works for you but I doubt it does for nearly all the rest of us.

My 10% correction comment was just a general statement.
 
I believe (basic joe opinion) we are going to feel a dip before the Fed makes the announcement - fear is too high that rates are going to be used to temper the inflation and a correction drop if rates are used to temper the setting. Tommorw creeped up quick... ;)
I'd be super surprised if the Fed doesn't hike tomorrow. I assume 25bp. I also think there's a good chance the market goes higher on that news. I also assume Trump will go ballistic if Warsh raises rates.
 
I'd be super surprised if the Fed doesn't hike tomorrow. I assume 25bp. I also think there's a good chance the market goes higher on that news. I also assume Trump will go ballistic if Warsh raises rates.
Typically a dip on rate hikes though I have heard what your saying elsewhere for a potential rise as well as the common theme of a quarter hike.
I simply didn't feel comfortable having all my eggs sitting in stocks. If it does start a drop and hype stacks on - that's my concern.

Bonds are in for a beating... maybe not as bad because it is so widely expected?
 
I'd be super surprised if the Fed doesn't hike tomorrow. I assume 25bp. I also think there's a good chance the market goes higher on that news. I also assume Trump will go ballistic if Warsh raises rates.
if 25bp then market falls by end of day. Reason? Not likely more hikes are not needed and slowing inflation is going to take a larger increment and more of them.

If raises a full 100bp then I expect the market to jump by end of day. If 50 bp then about flat by end of day.

I have no bets in place re a raise or amount of raise but one is needed. Tariffs (estimated $1500/year/household negative impact), the Iranian Non-War bill for the boom booms and the air base destructions and oil price increase (estimated $4500/year/household negative impact), and the deficit growing from Congress spending like drunken sailors and the 33% if National Debt debt financing maturing in next 12 months flipping that debt from as low as 2016-issued 0% expiring T-Bills to being 2026 5% T-bills/T-bonds. Ouch. The smoking hole in the foot which increased oil prices this year makes me happy to drive past gas stations in my 8 year-old EV which has had one new set of tires and two sets of wipers but no other service.
 
You're positive? Maybe I've been reading you wrong on this entire thread but I would have put you at cautious at best. It seems like you normally have a negative bias.

Inflation, interest rates and oil have all gone higher this year and yet so have stocks. Inflation has gone from about 2.4% to 3.4%. The 10 year has gone from roughly 4.15% to around 5%. WTI has gone from below $60 to over $100 now. And yet the S&P is up around 10%. I guess without the stellar earnings growth this year, it would be a little different. My point though that I've made many times is that it just rarely pays to worry about the vast majority of stuff and to try and jump in and out. Or to wait for a correction to buy. Maybe it works for you but I doubt it does for nearly all the rest of us.

My 10% correction comment was just a general statement.
You always think I’m bearish for some reason. I’m not sure how to clarify it as I have tried numerous times. My estimate is that the market is about 8% overvalued. The recent choppiness and good earnings has helped bring that in a little. 8% isn’t terrible so I stay with equities at full weight (although I hedge a little around option expirations). And we agree, for most people, they just save and invest and move on.

Maybe I am positive on the market, but not positive on the economy. Data is mixed so a person can paint a positive view ignoring the bad stuff or a negative view ignoring the good stuff. I still think construction is an important driver of general the overall economy. The housing market is a mess so we are just riding on the datacenter wave. That will come to an end at some point, particularly if these companies can’t turn that investment into tangible results. The irony is that if we see the benefits of AI it probably means people lose their jobs, or at least hiring slows. We are already seeing that at the entry level positions. Higher interest rates, higher prices, lower job growth are a bad trifecta. The good news is boomers are spending like they have an expiration date and the government continues to spend like a drunken sailor. Eventually the promises come due.
 
You always think I’m bearish for some reason. I’m not sure how to clarify it as I have tried numerous times. My estimate is that the market is about 8% overvalued. The recent choppiness and good earnings has helped bring that in a little. 8% isn’t terrible so I stay with equities at full weight (although I hedge a little around option expirations). And we agree, for most people, they just save and invest and move on.

Maybe I am positive on the market, but not positive on the economy. Data is mixed so a person can paint a positive view ignoring the bad stuff or a negative view ignoring the good stuff. I still think construction is an important driver of general the overall economy. The housing market is a mess so we are just riding on the datacenter wave. That will come to an end at some point, particularly if these companies can’t turn that investment into tangible results. The irony is that if we see the benefits of AI it probably means people lose their jobs, or at least hiring slows. We are already seeing that at the entry level positions. Higher interest rates, higher prices, lower job growth are a bad trifecta. The good news is boomers are spending like they have an expiration date and the government continues to spend like a drunken sailor. Eventually the promises come due.
I mean he's not wrong, your posts seem to focus on the negative.
 

Forum statistics

Threads
119,996
Messages
2,246,300
Members
39,073
Latest member
2DaPoint
Back
Top